
Government-Backed
Capital. Real
Human Guidance.
Last updated: August 2026
SBA loans can offer long terms for established small businesses, but the application process is document-intensive. Your Capital Advisor handles the paperwork, the lender matching, and the back-and-forth so you don't have to.

SBA Loans at a Glance
What is an SBA loan?
SBA loans are supported by the U.S. Small Business Administration, which can help lenders structure terms for qualifying businesses. The tradeoff is paperwork and timeline, which is exactly where a Capital Advisor earns their keep.

Long-Term Structure for Established Businesses
SBA programs can provide a longer repayment schedule for qualifying businesses. Your Capital Advisor will help you compare the structure with other options before you apply.
We Navigate the Paperwork With You
SBA applications require detailed documentation: financial statements, business plans, personal financial statements, and more. Your Capital Advisor prepares your file correctly the first time, avoiding the delays that sink most SBA applications.
Matched to the Right SBA Program
7(a), 504, and microloans each serve different purposes. We identify which program fits your situation instead of forcing you into a one-size-fits-all application.
One Point of Contact, Start to Finish
No bouncing between bank branches or call centers. One advisor manages your file from application to funding, keeping you informed at every stage of the process.
Which SBA Program Is Right for You?
The SBA offers multiple loan programs designed for different business needs. Your Capital Advisor will identify the best fit before you apply.
| SBA 7(a) | SBA 504 | Microloan | |
|---|---|---|---|
| Up To | $5M | $5.5M | $50k |
| Best For | Working capital, acquisitions, refinancing | Real estate, major fixed assets | Startup costs, small equipment |
| Term | Up to 10 yrs (25 for real estate) | Up to 25 yrs (real estate) | Up to 6 years |
| Down Payment | 10–15% | 10% | Varies |
Not sure which program fits? Talk to a Capital Advisor → Read our guide to bridging an SBA file.
If a closing date will not wait for SBA funding, an SBA bridge loan can cover the gap and be repaid from the SBA proceeds.
How do SBA loans work?
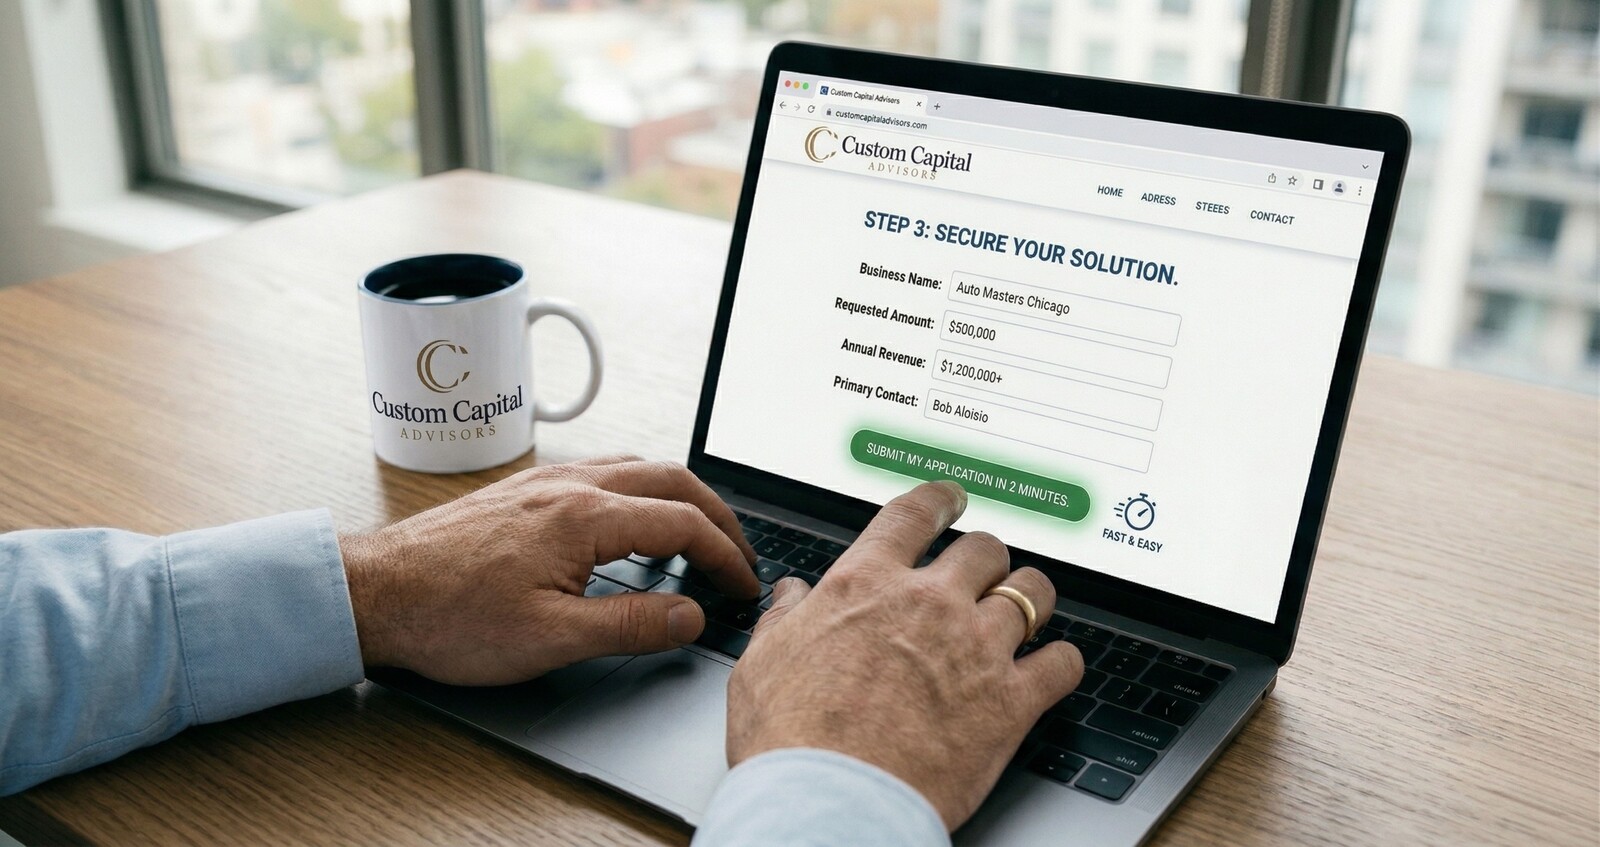
Apply & Share Your Goals
Submit your application and tell your Capital Advisor what the capital is for. They'll determine which SBA program fits your business, revenue profile, and use of funds.
We Prepare Your File
Your advisor compiles and reviews documentation before submission, the top reason SBA applications get delayed or denied is incomplete or poorly structured paperwork. We get it right the first time.
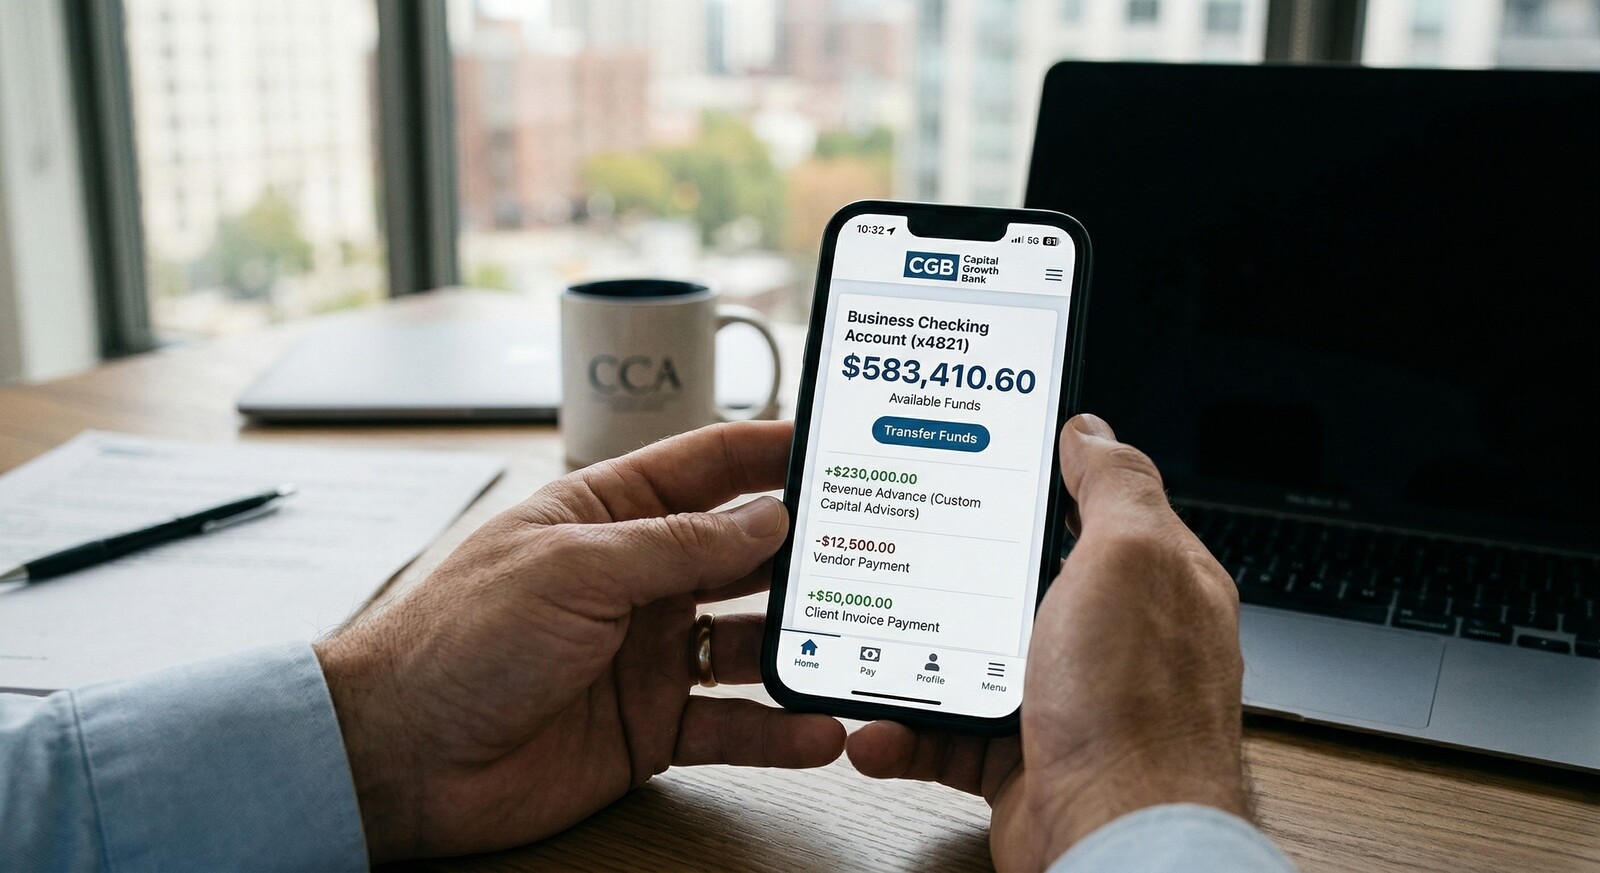
Get Funded
Once a lender approves the file, funds are disbursed according to the loan structure. The timeline is often 30 to 60 days, depending on the program and the completeness of the application.
What can you use an SBA loan for?
SBA loans are best suited for long-term, strategic capital needs where an extended repayment schedule is the priority.
Business Acquisition
Buy an existing business or buy out a partner with long-term financing structured for ownership transitions.
Commercial Real Estate
Purchase or renovate the building your business operates from, with terms up to 25 years and lower monthly payments.
Working Capital & Refinancing
Consolidate existing obligations or fund operations with a structured SBA loan.
How do SBA loans compare to other financing?
| SBA Loan | Term Loan | Small Business Loan | |
|---|---|---|---|
| Up To | $5M | $500k | $1.5M |
| Term | Up to 25 years | Up to 12 years | 4–24 months |
| Funding Speed | 30–60 days | 3 business days | 24 hours |
| Time in Business | 2+ years | 2+ years | 6+ months |
| Best For | Long-term strategic capital | Strategic mid-size investment | Fast working capital |
Not sure which product fits? Talk to a Capital Advisor →
How do you qualify for an SBA loan?
Most SBA lenders look at the same core profile: an established business with a track record, steady revenue, a reasonable personal credit history, and owners who can show the loan fits the business plan. Two or more years in business is typical, though some programs work for younger companies with strong financials. Lenders also weigh your debt service coverage, meaning whether current cash flow can comfortably carry the new payment.
None of this is a pass-fail checklist, and no broker can promise an approval. What we can do is review your financials before anything is submitted and tell you honestly whether an SBA program is a realistic fit or whether a different structure serves you better. For the fuller borrower-side picture, our guide to business loan requirements walks through what lenders look for in any application.
What documents do you need to apply for an SBA loan?
Expect to provide business tax returns (usually two to three years), personal tax returns for each owner with 20 percent or more ownership, year-to-date financial statements, a debt schedule, and bank statements. Depending on the program and the use of funds, lenders may also ask for a business plan, purchase agreements, or real estate documents.
The paperwork is the part that stalls most applications. Preparing a complete, well-organized file the first time is most of the value an advisor adds, and it is the difference between a file that moves and one that sits in a queue collecting follow-up requests.
How much is the down payment on an SBA loan?
Down payment expectations vary by program and purpose. Purchases and projects financed under the 7(a) and 504 programs typically require an equity injection from the borrower, with the exact figure set by the lender based on the deal, the collateral, and the borrower's profile. Some uses, like working capital for a strong existing business, may require less up front.
Treat these as typical ranges, not commitments. The honest answer for your situation comes after a lender reviews your documents, and we will tell you what to expect before you commit to anything.
Which industries use SBA loans most?
SBA programs fit capital-intensive, established operations especially well. Manufacturing businesses use them for equipment and facility purchases. Commercial construction firms use them for equipment and expansion. Healthcare practices use them for acquisitions and buildouts, and restaurants for renovations and second locations. If your industry is not listed here, that does not rule you out; it just means the fit conversation matters more.
Common Questions
Great Terms Take
the Right Guidance.
Apply today. A Capital Advisor will review your business, identify the right SBA program, and manage your application from start to finish.