
Small Business
Cash Flow
Loans
Last updated: July 2026
If delayed receivables or seasonal dips are holding you back, access unsecured funding to stabilize cash flow and fuel growth. Apply online and get approved in as little as 4 hours.
Financing at a Glance
When do you need a cash flow loan?
Revenue cycles don't align with expense schedules. We provide the capital to bridge that gap, quickly, without collateral, and without the friction of traditional bank lending.

Unsecured, No Collateral Required
Cash flow loans are approved based on your business's revenue performance, not on pledging equipment, real estate, accounts receivable, or personal assets. If your business generates qualifying revenue, you can access capital.
Faster Than Any Bank Can Move
Traditional lenders take weeks. We deliver decisions in as little as 4 hours and fund within 24 hours of acceptance. When payroll is due tomorrow or a supplier invoice can't wait, speed is the difference between disruption and continuity.
Flexible Repayment That Fits Your Cycle
Choose between daily or weekly ACH repayment, or a Revenue Advance with repayment that adjusts as a percentage of your revenue, so slower periods mean smaller payments automatically.
No Restrictions on How You Use It
Cover payroll, pay rent, restock inventory, fund marketing, hire staff, or anything else your business needs. Unlike SBA loans or equipment financing, working capital has no use restrictions.
How do business cash flow loans work?
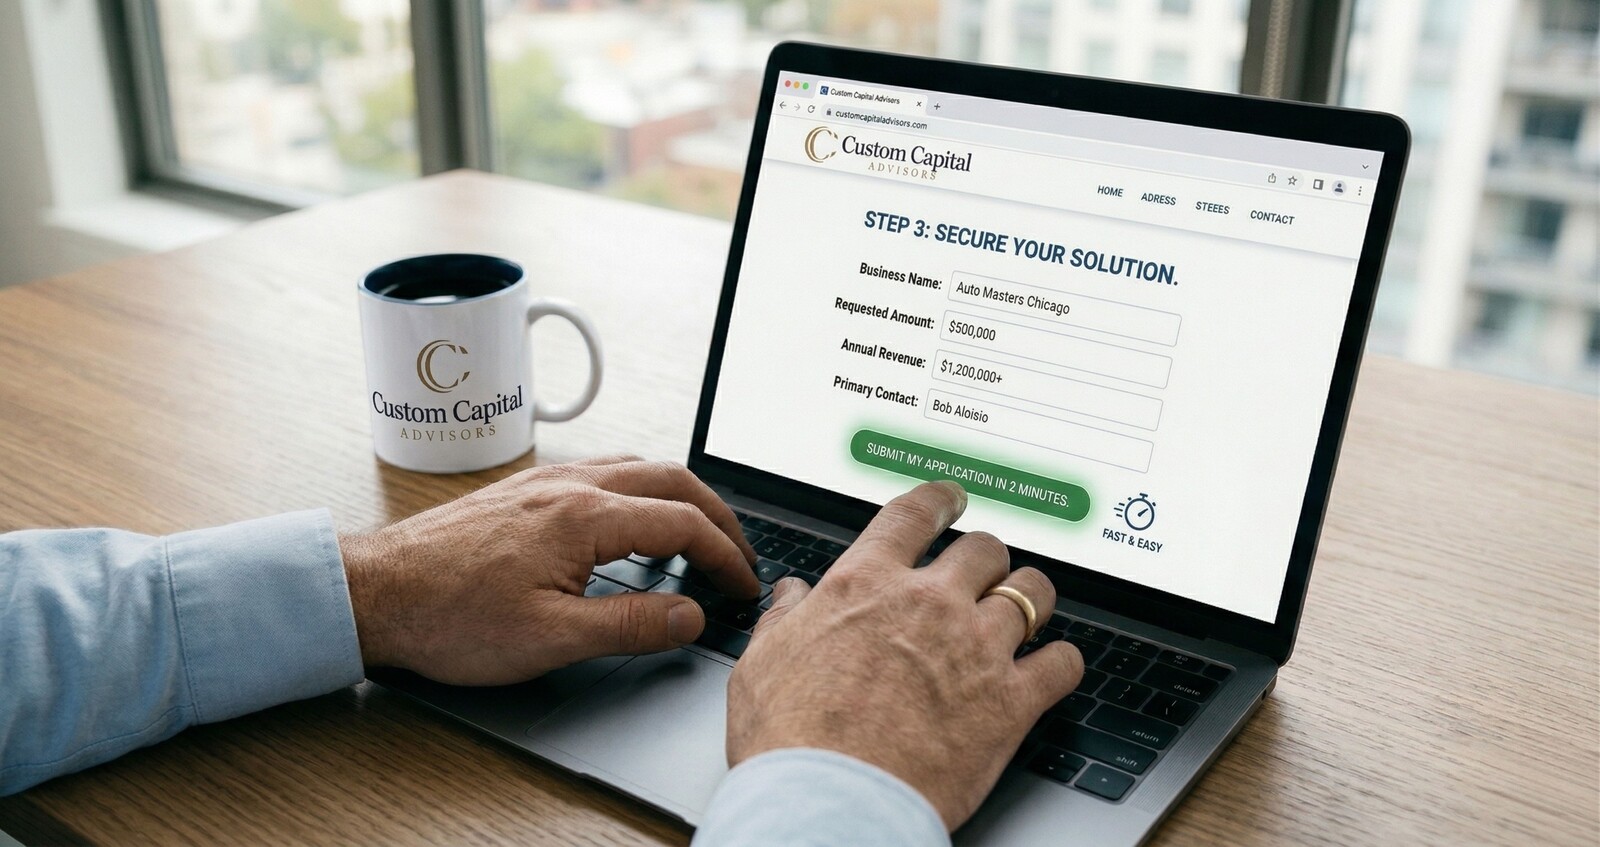
Apply Online in Minutes
Submit a brief application and connect with a dedicated Capital Advisor. Explain your cash flow situation, seasonal slowdown, delayed receivables, payroll gap, and they'll guide you toward the right structure.
Get a Decision
Your advisor reviews your revenue profile and presents a clear funding offer with transparent terms. Often in as little as 4 hours, with no excessive paperwork, no unnecessary delays.
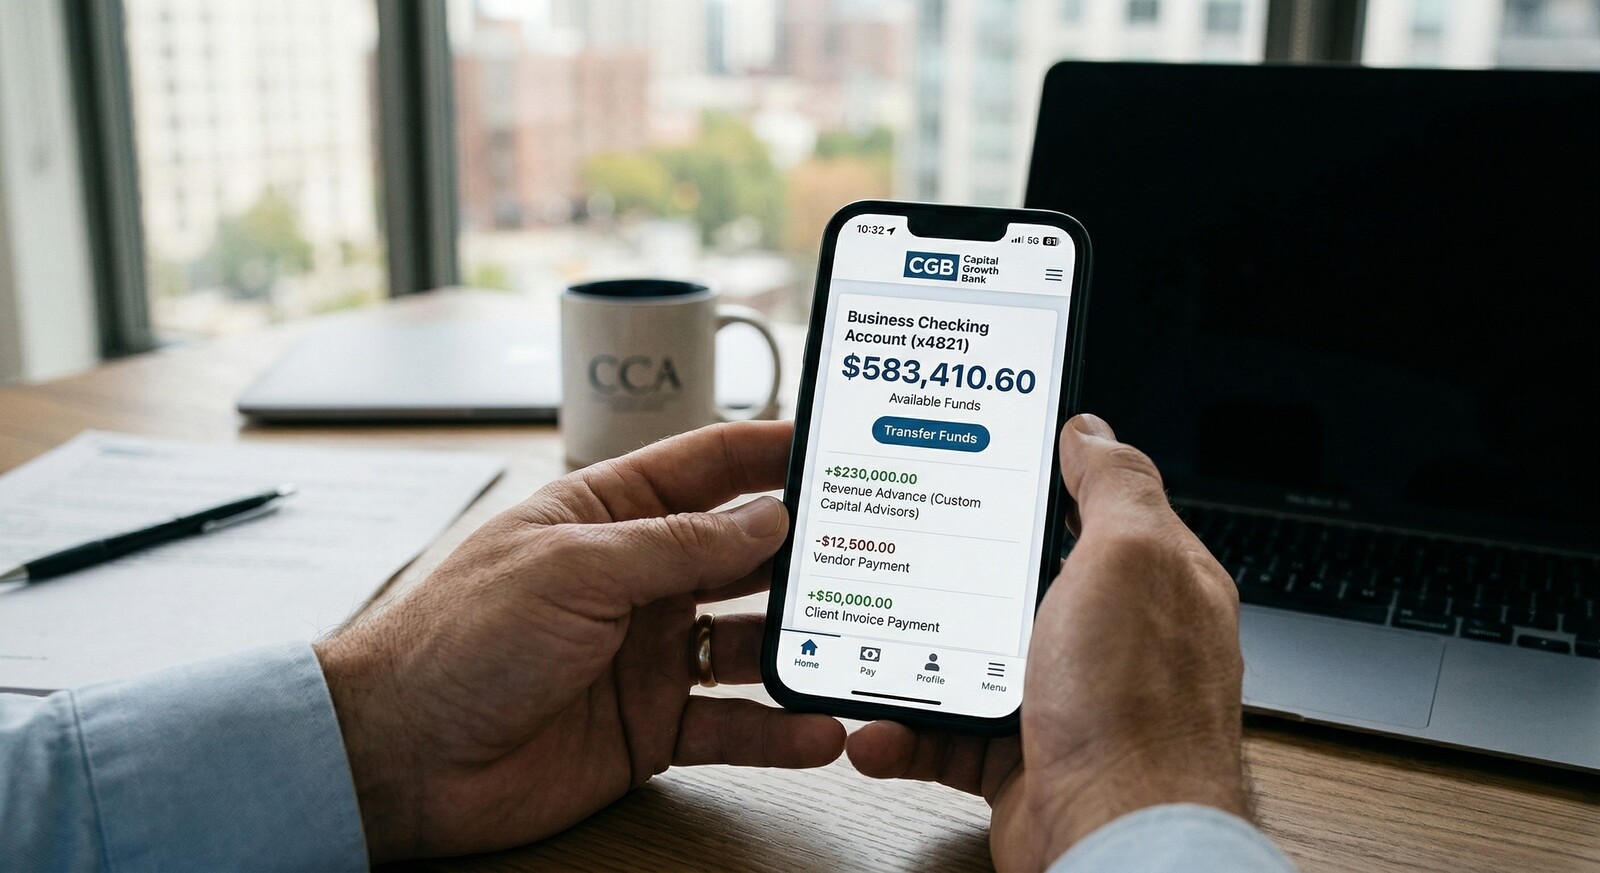
Access Your Funds
Receive a lump-sum deposit as fast as 24 hours after accepting your offer. Cover payroll, pay suppliers, restock inventory, or handle any other operational priority, immediately.
How do you qualify for a cash flow loan?
Qualification for cash flow financing looks different from qualification for a bank term loan. A bank underwrites your balance sheet and your history. A cash flow lender underwrites the money moving through your account right now, which is why a business that a bank would decline on a thin credit file can still be a straightforward approval here.
Nothing on this page is an approval or a rate. What a lender will actually offer depends on the documents, and no one at CCA will tell you otherwise before a lender has reviewed your file. For the product-by-product picture, see our guide to business loan requirements.
What are the requirements for a business loan of this type?
Most cash flow lenders start from four things: time in business, monthly revenue, business bank statements, and how your deposits behave across a month. Six months of operating history and consistent deposits will open more doors than a strong credit score with three months of history will.
What do you need for a business loan application?
The usual first ask is three to six months of business bank statements, a completed application, and a voided check. Some programs add a profit-and-loss statement or a recent tax return, and asset-backed structures add a schedule of what is being pledged. We tell you which list applies before you start gathering, rather than after.
What credit score is needed for a business loan?
There is no single number, and anyone who quotes you one has not seen your file. Credit is one input among several for cash flow products, and it usually influences pricing more than it decides approval. Revenue consistency carries more weight here than it does on an SBA or conventional bank loan, where credit is closer to a gate.
How important are business bank statements and yearly deposits?
They are the core of the file. A lender reading three to six months of statements is looking for deposit volume, deposit frequency, negative days, and whether the pattern is steady or lumpy. A business with seasonal swings is not disqualified by them, but the structure that fits will usually be one that flexes with the cycle rather than a fixed monthly payment.
What can you use a cash flow loan for?
Cash flow financing provides flexible working capital to manage revenue fluctuations, cover expenses, and invest in growth, without pledging collateral.
Stabilize Operations
Cover payroll, rent, utilities, and recurring expenses during receivables delays or seasonal slowdowns, keeping operations consistent even when revenue fluctuates.
Growth & Expansion
Hire employees, increase marketing spend, expand locations, or launch new products and services with capital that supports strategic growth without draining reserves.
Inventory & Working Capital
Prepare for peak seasons, stock additional inventory, upgrade technology, or replace critical equipment to keep your business efficient and competitive.
What are the best financing options for cash flow gaps?
Choose from cash flow loan options structured to match your revenue cycle, business goals, and repayment preferences.
Small Business Loan
Lump-sum working capital with no use restrictions. The most straightforward way to stabilize cash flow and cover immediate business expenses. See our working capital loans.
Learn MoreRevenue Advance
Upfront capital repaid as a percentage of your daily revenue, with payments automatically adjusting on slower days. Ideal for businesses with variable cash flow.
Learn MoreLine of Credit
Revolving access to capital: draw what you need, repay when receivables clear, and draw again. The most flexible tool for ongoing cash flow management.
Learn MoreEquipment Financing
Preserve working capital by financing equipment purchases over time. Own the asset outright at the end while keeping cash available for operations.
Learn MoreTerm Loan
Long-term structured repayment for larger planned investments. Fixed payments make budgeting predictable over a defined repayment period.
Learn MoreNot Sure Which Fits?
Your Capital Advisor will review your revenue profile and identify the cash flow financing structure that best fits your business cycle and goals.
Let's TalkHow quickly can you get funding for a cash flow gap?
Speed is usually why a business is on this page rather than at a bank. Timelines vary by product and by how complete the file is when it arrives, and the honest answer is a range rather than a promise. Our guide covers how fast a business can get funded product by product.
How fast can funding be approved?
Decisions on revenue-based products can come back in as little as 4 hours once statements are in. A line of credit typically takes a day or two. SBA and conventional bank options run weeks, which is exactly why they are the wrong tool for a gap that closes this month. Funding can follow as fast as 24 hours after approval on the quicker products.
What slows an application down?
Almost always the documents. Missing months of statements, a bank connection that will not link, or a mid-application change to the amount requested. The second most common cause is applying to several lenders at once, which shows up in the file and makes every one of them more cautious.
Common Questions
Stop Letting Cash Flow
Hold Your Business Back.
Apply today and get a decision in as little as 4 hours. Capital in hand within 24 hours of acceptance.