
Manufacturing
Financing,
Funding & Loans
Last updated: July 2026
We've provided capital to all types of manufacturing businesses, from small shops to mid-market producers, with financing for materials and production inputs structured around how manufacturing companies actually operate. Custom Capital Advisors works with manufacturers on the full range of manufacturing capital needs, from a single machine to a multi-line plant expansion.

Financing at a Glance
What makes manufacturing financing different?
Long production cycles, large raw material orders, fluctuating demand, and skilled labor costs. Manufacturing businesses have capital needs that most lenders don't fully appreciate. We do.
Underwriting Built for Production Cycles
Manufacturing revenue doesn't always arrive in neat monthly increments. We account for large order cycles, seasonal demand, and delayed receivables in our underwriting, rather than penalizing you for how the industry actually works.
Equipment Financing for Production Lines
Machinery, automated systems, CNC equipment, and specialized production tools are capital-intensive. Our equipment financing lets you acquire what you need without tying up working capital in large upfront purchases.
Raw Material Capital Available Fast
Supplier pricing windows and minimum order requirements don't wait for bank approvals. We move in as little as 24 hours so you can secure materials when pricing and availability are favorable.
Skilled Workforce Protection
Replacing trained manufacturing labor is costly and slow. Use working capital to maintain full payroll through slow periods, contract gaps, or while scaling up to meet a major new order.
For a worked example, our specialty manufacturing case study walks through how one manufacturer structured financing around a production bottleneck, from the first conversation to funding.
How does manufacturing financing work?
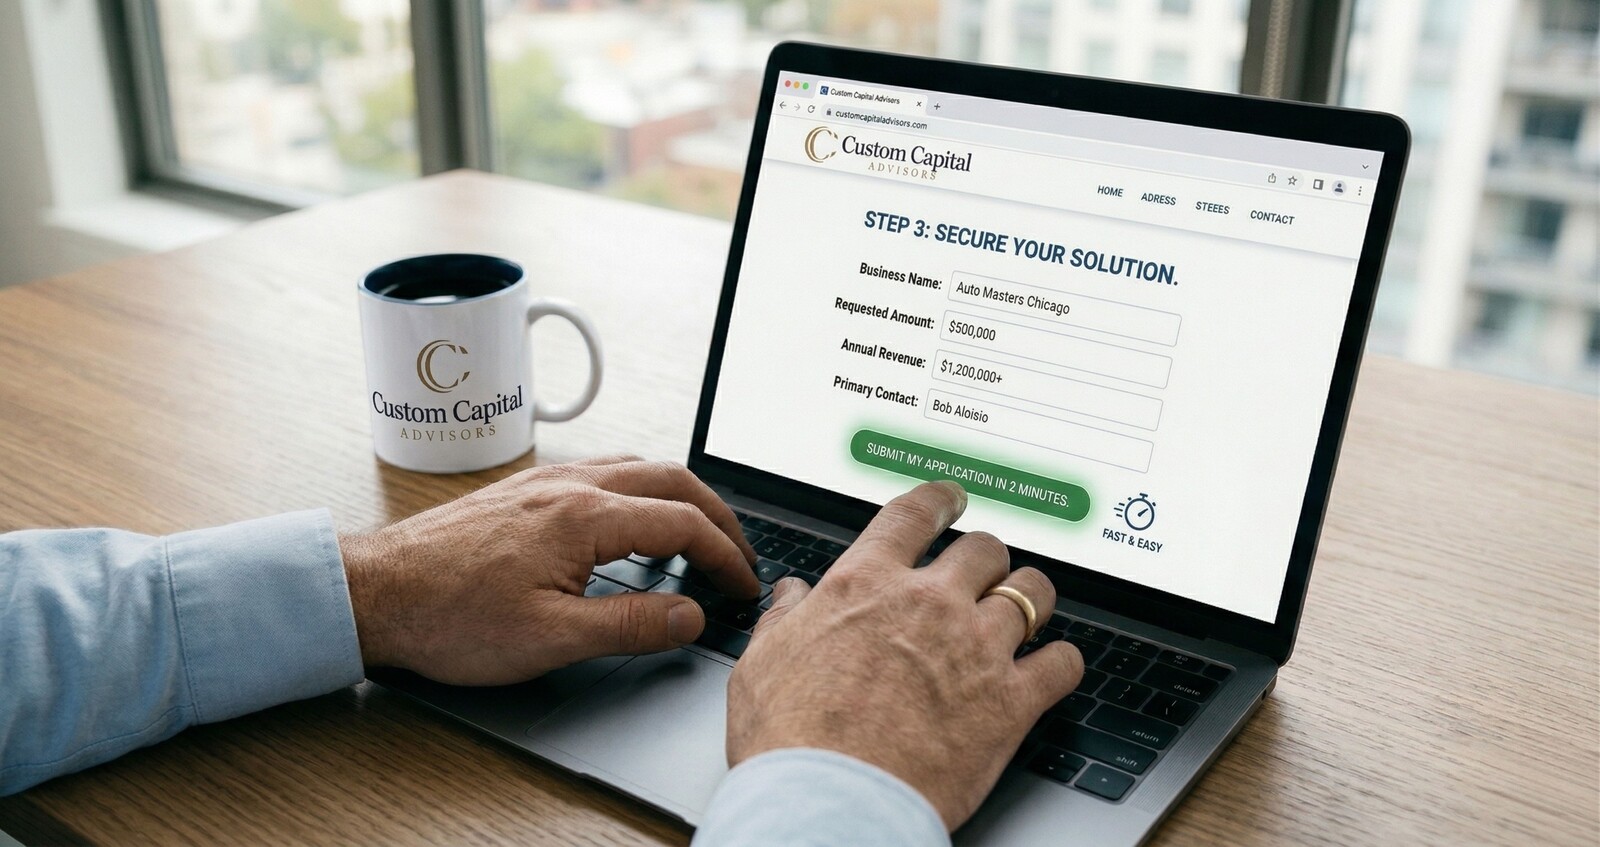
Apply Online in Minutes
Submit a quick application and connect with a dedicated Capital Advisor. Describe what you need the capital for (materials, equipment, payroll, or expansion) and they'll guide you from there.
Get a Decision
Your advisor reviews your business, revenue, production history, and financials, then presents a financing offer structured around your manufacturing operation, often same-day.
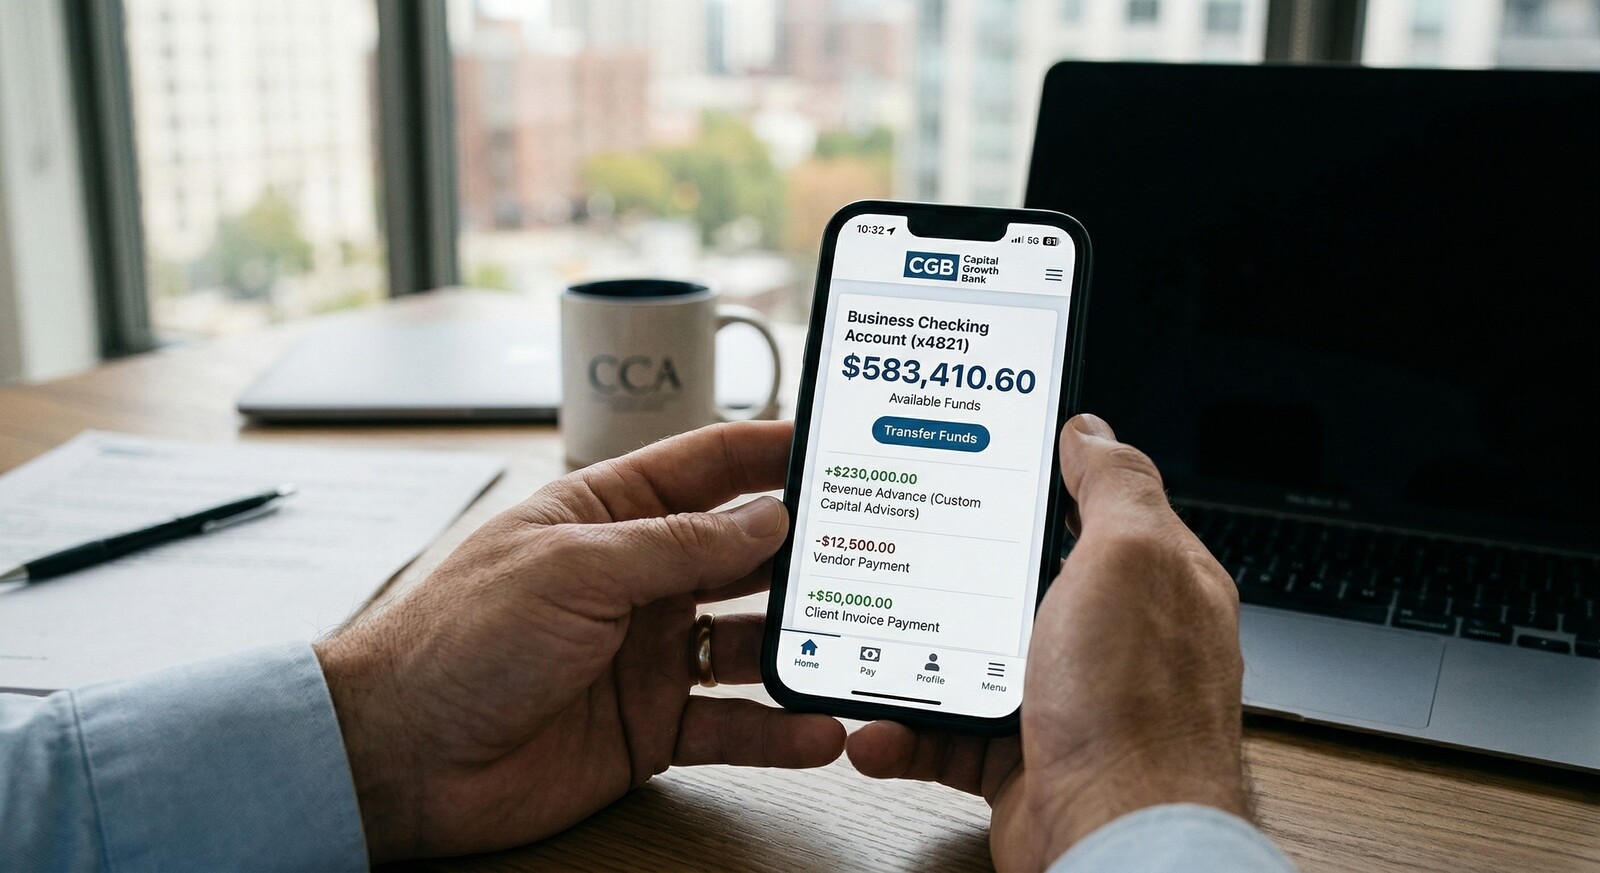
Access Your Funds
Receive funds as fast as 24 hours after accepting your offer. Purchase materials, pay suppliers, cover payroll, or invest in equipment, on your schedule.
What can you use manufacturing financing for?
From raw materials to payroll to expansion, manufacturing loans are designed to help keep production running and businesses growing.

Stock Raw Materials & Inventory
Maintain a steady supply of raw materials and finished goods to keep production moving. Lock in bulk pricing and avoid costly production halts due to supply shortages.
Expand Facilities & Capacity
Growth is good, but space and equipment constraints can limit it. Use business capital to lease or build additional production space, add lines, or scale your facility to meet demand.

Cover Payroll During Production Gaps
Skilled manufacturing labor is hard to replace. Use financing to maintain full payroll between large orders, during slow seasons, or while waiting on delayed receivables from major clients.
Looking for an investment firm for manufacturing businesses?
It depends on which kind of money you are after, and the two are genuinely different.
Custom Capital Advisors is a business lending brokerage. We arrange debt financing for manufacturers: term loans, equipment financing, lines of credit, asset-based facilities, invoice factoring, SBA loans, and revenue advances. You borrow, you repay, and you keep every share of your company. We are not a lender ourselves. We take your file to the lenders whose appetite matches your situation and we manage the process from there.
An equity investment firm is a different party doing a different thing. A private equity group, a growth equity fund, or a strategic investor buys a stake in your business. You are not repaying anything, but you have sold part of what you own and usually taken on a partner with a say in how the company runs.
Which one fits depends on what the money is for:
Debt usually fits better when the need is working capital, a specific machine, materials for a contract you have already won, payroll across a slow collection cycle, or a facility expansion with a clear payback. These are financeable events with a defined end date, and giving up ownership to fund them is expensive.
Equity usually fits better when the need is large, open-ended, and tied to a change in the shape of the business: buying a competitor, entering a market that will take years to pay off, or funding a build-out with no near-term cash flow to service a loan against.
Plenty of manufacturers need both, in sequence. If your situation is genuinely an equity one, we will say so and point you in a useful direction rather than push a loan at you. If it is a debt situation, that is the part we do, and we do it across the full range of manufacturing capital needs.
Manufacturing business funding: what are the options?
Manufacturers have more usable options than most sectors, because a manufacturing balance sheet tends to hold real, appraisable assets. What follows is the practical menu, roughly in order of how often it fits.
Equipment financing. The machine secures its own loan, which is why this is usually the cheapest money available to a manufacturer and why it is where most conversations start. It covers CNC machines, presses, lines, material handling, and in many cases installation and freight. Used equipment is financeable, though terms tighten with age.
Invoice factoring. If you sell to other businesses on 30, 60, or 90 day terms, factoring converts those invoices into cash now instead of at maturity. It is sized by your receivables rather than by your credit, which makes it reachable for younger shops and for companies growing faster than their balance sheet.
Asset-based lending. A facility sized against a borrowing base of receivables, inventory, and sometimes equipment and real estate. It suits manufacturers carrying real inventory who need a facility that grows as the business grows.
Lines of credit. Revolving access for the recurring gaps: a materials buy before a production run, payroll across a slow month, a deposit on a large order. You draw what you need and pay interest on the drawn balance.
Term loans. A lump sum on a fixed schedule, for a defined project with a defined payback: a facility expansion, a large capital purchase, a plant relocation.
SBA loans. Longer terms and generally the lowest cost available, in exchange for the heaviest documentation and the longest timeline. Strong for acquisitions, real estate, and large expansions when you can wait.
Revenue advances. Fast working capital repaid from a share of revenue. The most expensive option on this list, and worth using only when speed genuinely decides the outcome, such as a materials buy that has to happen this week to hold a contract.
Most manufacturers we work with end up with a combination rather than a single product, because a machine purchase and a payroll gap are not the same problem and should not be financed the same way. Which combination is right depends on your margins, your collection cycle, your existing debt, and what the money is actually for. That is the conversation to have before you start applying anywhere.
How manufacturing capital investment gets financed
Capital investment is where manufacturing financing gets its own logic, because the asset you are buying usually helps pay for itself.
Start with the payback question, because it drives the structure. A machine that adds capacity you have already sold produces a return you can measure, and that measurement is what determines how long the financing should run. Match the term to the useful life of what you are buying. Financing a fifteen-year press over three years starves your cash flow. Financing a three-year asset over ten leaves you paying for something you have already replaced.
From there the structure follows the purchase:
A single machine or line is usually equipment financing, secured by the asset itself, often at a high advance rate because the collateral is specific, appraisable, and resaleable.
A multi-machine build-out may be better as a term loan or an equipment line of credit, so you are not opening a separate facility for every purchase and paying to close each one.
Real estate and major facility work points toward SBA, which offers the longest terms and lowest cost on this kind of spend, provided the timeline allows for it.
An acquisition of another shop typically blends financing types, because you are buying equipment, receivables, inventory, and goodwill in one transaction, and each piece underwrites differently.
Two things consistently decide how well this goes. The first is documentation: quotes or invoices for what you are buying, your last two or three years of financials, and a clear statement of what the investment does for the business. The second is timing, and it runs the other way from how most people plan it. Line up the financing before the machine is on order, not after. Manufacturers who arrive with a signed purchase order and a delivery date have less room to negotiate than manufacturers who arrive with a plan.
We will show you realistic cost ranges for each route. We will not quote you a rate or tell you what will be approved before a lender has reviewed your file.
How do manufacturers finance a capital investment?
Most manufacturing capital investment falls into one of four shapes, and each has a financing structure that fits it better than the others. A machine or production line purchase is usually equipment financing, because the asset secures the deal and the repayment horizon can be matched to the working life of the machine. A plant expansion or a facility build-out is usually a term loan or an SBA loan, because the payback runs over years, not months. Raw materials bought against a specific purchase order are usually working capital or invoice factoring, because the need appears and clears inside one production cycle. And the gap between shipping an order and being paid ninety days later is usually a line of credit. Manufacturing capital investment is the kind of spend where matching the horizon matters most. A five-year machine financed over nine months puts the whole business under strain to buy an asset that will still be earning in year four.
What financial services do manufacturers actually need?
Manufacturers rarely need one product. A typical file we work carries an equipment need, a materials need, and a receivables gap that all move on different clocks. What manufacturing owners tell us they want from financial services for manufacturers is not a bigger menu, it is someone who understands why the three cannot be solved with the same instrument. That is the job of a manufacturing expansion advisor, and it is the job we do: read the operation, map each need to the structure that fits it, and take the file to the lenders whose programs actually serve industrial borrowers. We are a brokerage. The lender makes the credit decision. Our work is making sure the right lenders see a well-built file, and telling you plainly when the answer is to wait a quarter rather than to borrow now.
Common Questions
Keep Production
Running Strong.
Don't let capital constraints slow your production. Apply today and get a decision, often within hours.