
Business
Equipment
Loans & Financing
Last updated: July 2026
Keep your operations running with high-quality, functional equipment. Finance repairs, upgrades, and new acquisitions without depleting your working capital.

Financing at a Glance
When should you finance equipment instead of buying it outright?
The right equipment drives revenue. Equipment Financing lets you acquire what you need today, while spreading the cost over time and preserving your working capital for daily operations.
Preserve Working Capital
Equipment purchases can be significant one-time expenses. Financing spreads that cost over time, keeping your cash reserves available for payroll, inventory, marketing, and other operational priorities.
You Own the Asset
Unlike leasing, Equipment Financing means the asset belongs to your business. You build equity in the equipment itself, and ownership transfers fully at the end of the repayment period with no residual payment or return obligation.
Fast Enough for Urgent Situations
A broken piece of critical equipment can stop your business. We move fast, delivering decisions often within hours and funding within 24 hours, so downtime is minimized and operations resume quickly.
Works Across Every Industry
We finance equipment for construction, manufacturing, medical, food service, retail, transportation, and virtually every other business vertical. If it's essential to your operations, it likely qualifies.
Is it better to lease or finance equipment?
It depends on how long the equipment stays useful relative to how long you are paying for it.
Financing builds ownership. You hold the asset at the end, you build equity in it as you pay, and across the full term it usually costs less. Leasing keeps the monthly payment lower and makes it straightforward to hand the equipment back when it dates.
The deciding question is the replacement cycle. A machine that holds its value for a decade usually favors ownership. Diagnostic or computing equipment that is obsolete in three years often favors a lease, because you are paying for use rather than for an asset you will want to be rid of.
There is a third path worth pricing before you choose either: finance the purchase and sell the old unit yourself rather than trading it in. Owners often assume a trade-in is the only option, and the private resale is sometimes worth more than the dealer credit.
A Capital Advisor can put the two structures side by side against your actual replacement cycle, which is a faster way to decide than reasoning about it in the abstract.
Can you finance used or refurbished equipment?
Yes, and it is more common than most owners expect.
What changes is not whether financing exists but which structures are available. Lenders look at the age of the unit, how active its resale market is, and whether you are buying from a dealer or a private party. Those three things shape the terms on offer.
A private-party purchase usually needs more documentation than a dealer purchase, because the lender has less to verify the machine and the transaction against. Expect to supply the bill of sale, serial numbers and often an inspection or appraisal.
Send us the listing and the seller details and we will tell you which lenders in our network work with that age and category before you commit to anything.
What if your company is owned by a private equity firm or another investor?
Sponsor-backed and investor-owned companies finance equipment routinely. The ownership structure changes the paperwork, not the range of options.
Lenders will want to understand the ownership chain, who has authority to sign, and how the parent relationship affects guarantees. Raise it at the start rather than at closing. It shapes which lenders are a fit, and discovering it late is the most common reason a sponsor-backed file has to be re-papered with a different lender.
We cannot tell you a personal guarantee will be waived, and you should be cautious of anyone who does before reading your documents. What we can do is put the ownership structure in front of lenders whose credit boxes accommodate it. Our guide to the personal guarantee on a business loan covers what lenders are actually asking for and why.
How does equipment purchase financing work?
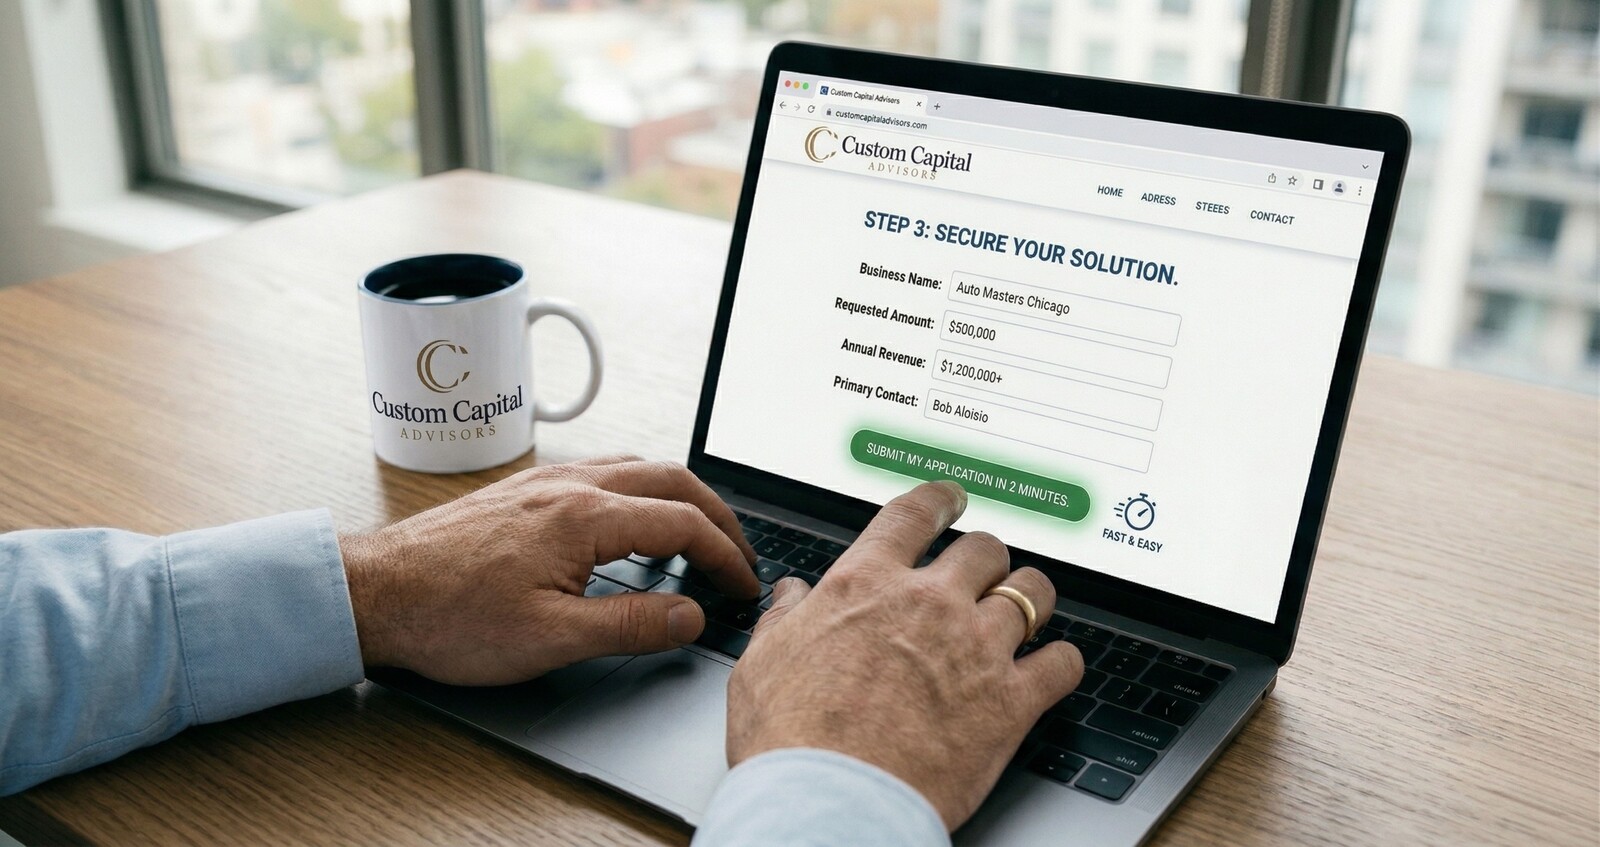
Apply Online in Minutes
Submit a brief application and connect with a dedicated Capital Advisor. Describe the equipment you need (what it is, its approximate value, and whether it is a purchase, repair, or upgrade) and they'll guide you toward the right structure.
Get a Decision
Your advisor reviews your revenue profile and the equipment being financed, then presents a clear funding offer with transparent terms. Often the same day, no excessive paperwork or unnecessary delays.
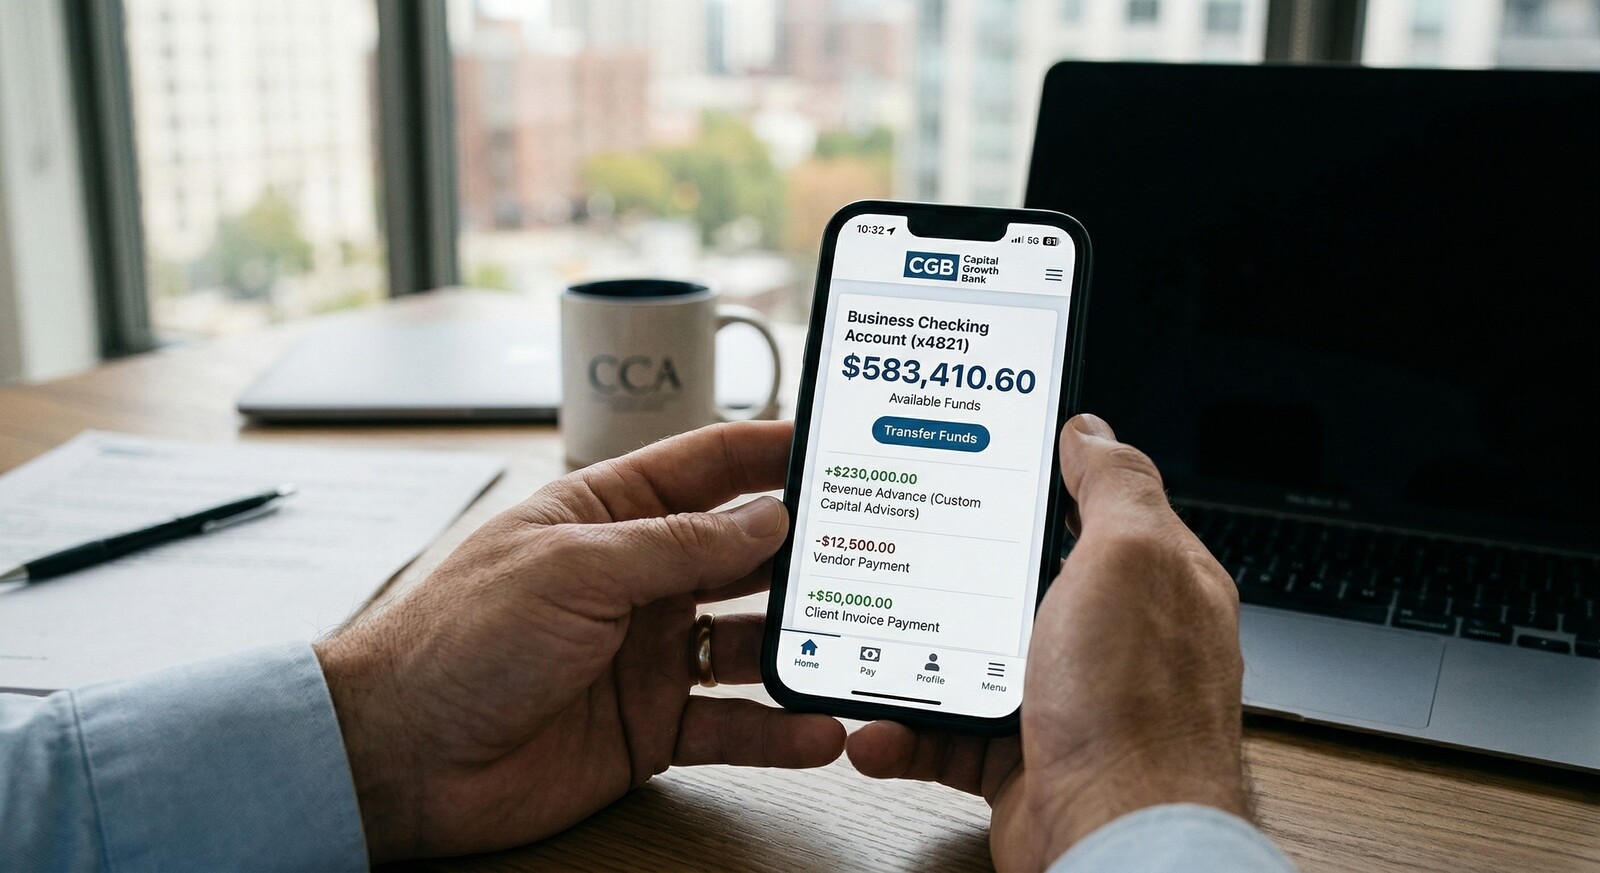
Get Your Equipment
Receive your funds as fast as 24 hours after acceptance. Purchase, repair, or upgrade the equipment your business needs, and start generating returns on that investment immediately.
What equipment can you finance?
Equipment loans are purpose-built for keeping your business's operational infrastructure in top condition, covering repairs, upgrades, and new acquisitions across every industry.
Repairs
Equipment breakdowns halt operations and cost more the longer they go unfixed. Get fast capital to cover essential repairs and keep your business running without disruption.
Upgrades
Replace outdated machinery, technology, or tools with equipment that improves efficiency, reduces downtime, and keeps your business competitive in the market.
New Acquisitions
Finance net-new equipment purchases, from commercial kitchen appliances to manufacturing machinery, to expand capacity and take on more business without depleting reserves.
What are the best financing options for buying equipment?
Not every equipment situation calls for the same structure. Explore our products to find the right fit for your acquisition, repair, or upgrade.
Equipment Financing
Purpose-built for equipment acquisition. Finance the purchase of machinery, vehicles, technology, or any business-critical asset, and own it outright at the end of the term.
Learn MoreSmall Business Loan
Lump-sum working capital with no restrictions. Ideal for repairs, smaller equipment purchases, or situations where Equipment Financing doesn't apply.
Learn MoreRevenue Advance
Upfront capital repaid as a percentage of your daily revenue. A flexible alternative for equipment expenses when your revenue is variable.
Learn MoreLine of Credit
Revolving access to capital, draw for equipment needs as they arise, repay, and draw again. Good for ongoing maintenance and smaller recurring equipment expenses.
Learn MoreTerm Loan
Long-term structured repayment for major equipment investments. Fixed payments and a defined term make planning and budgeting straightforward.
Learn MoreNot Sure Which Fits?
Your Capital Advisor will evaluate your equipment situation and recommend the financing structure that makes the most sense for your business.
Let's TalkCommon Questions
Get the Equipment
Your Business Needs.
Apply today and get a decision often within hours. Capital in hand within 24 hours of acceptance, so downtime stays minimal and operations keep moving.