
Business Term Loans
and Long-Term
Financing
Last updated: August 2026
A business term loan is a lump sum of capital repaid over a fixed period on a predictable monthly schedule. A long-term business loan is the same structure stretched over a longer horizon, usually five years or more, which lowers the monthly payment and suits investments that pay back slowly. Custom Capital Advisors is a brokerage, so we take your file to the lenders whose term-loan programs actually fit it, and we tell you when a term loan is the wrong tool.

Term Loan at a Glance
What is a business term loan?
Term loans we arrange provide the capital depth and structured repayment that established businesses need to execute their biggest plans, without disrupting day-to-day operations.
Predictable, Fixed Monthly Payments
Unlike daily or weekly repayment schedules, term loans are repaid monthly, making it simple to plan your cash flow and budget around a consistent, known payment.
Longer Terms for Larger Investments
With terms up to 12 years, you can finance significant capital projects at a payment level that doesn't strain your operating budget. Match the repayment horizon to the life of the investment.
A Real Advisor Reads Your File
Every term loan file is read by a dedicated Capital Advisor, not sorted by an algorithm. We look at your business history, your industry, and where you are heading, then take the file to the lenders in our network whose term-loan programs actually fit it. We are a brokerage, so the lender makes the credit decision and we make sure the right lenders are the ones seeing your file.
Transparent Terms, No Surprises
Your offer will clearly outline the rate, term, monthly payment, and any fees before you accept. What you see is what you get: no buried conditions, no fine-print surprises at closing.
What is a long-term business loan?
A long-term business loan is a term loan repaid over roughly five to twelve years rather than months. The label describes the repayment horizon, not a separate product. Lenders generally sort term debt into three bands: short-term, repaid in about three to eighteen months; medium-term, roughly one to five years; and long-term, five years and beyond.
The horizon is the whole decision. A longer term means a smaller monthly payment and more total interest paid over the life of the loan. A shorter term costs less overall and takes a bigger bite out of every month's cash flow. Match the horizon to the life of what you are buying. Financing a twelve-year building improvement over eighteen months puts strain on the business for no reason, and financing eighteen months of inventory over twelve years means you are still paying for goods you sold years ago.
How does a business term loan work?
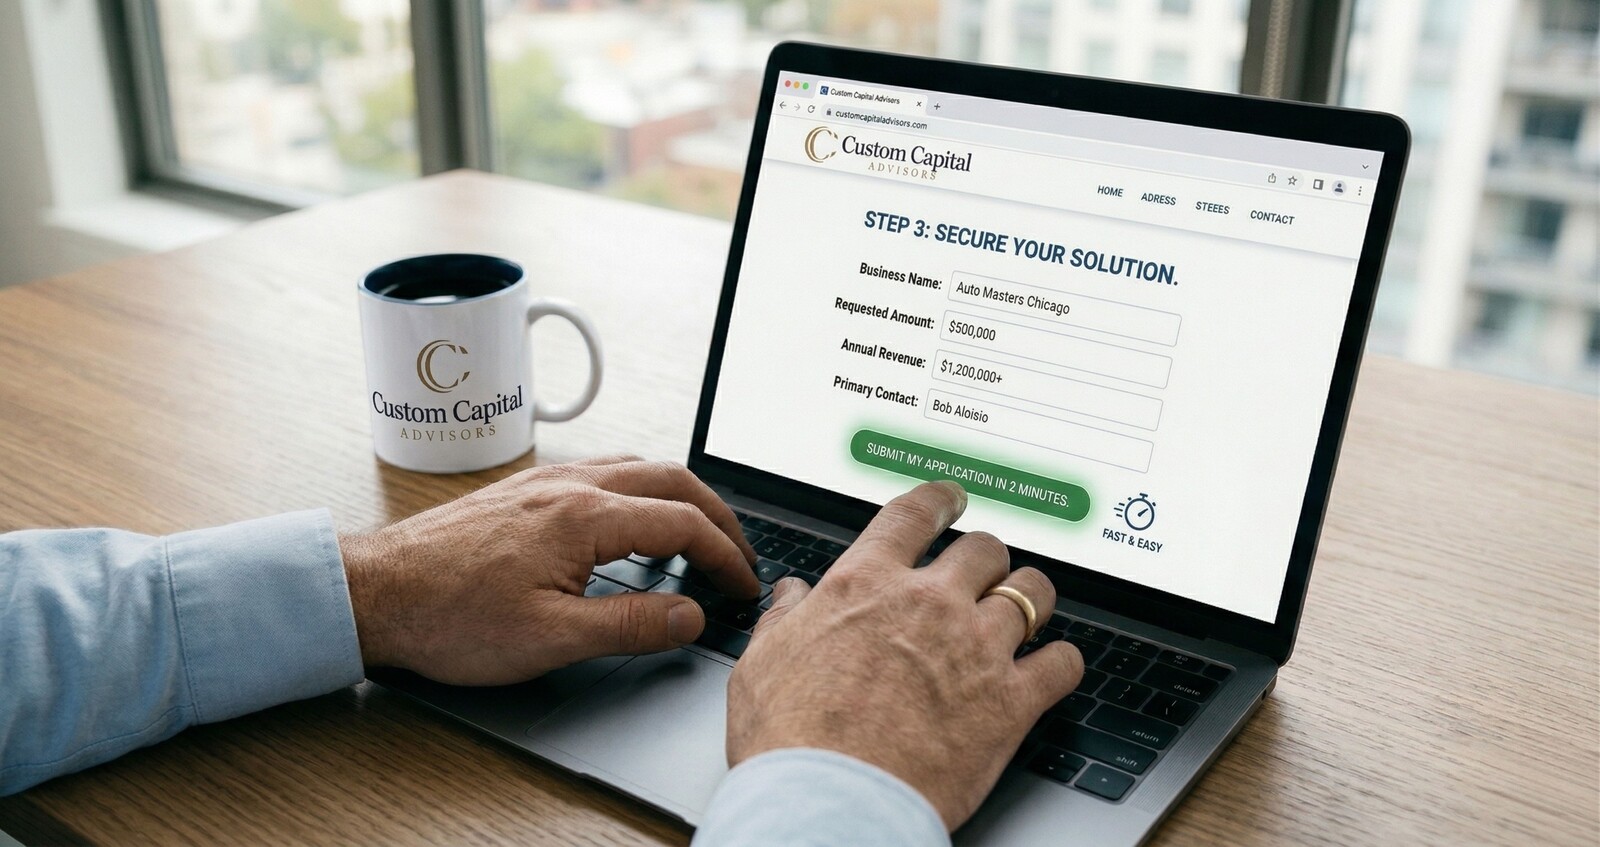
Apply Online in Minutes
Submit your application and connect with a dedicated Capital Advisor. Share your business goals and the investment you're planning, they'll guide you through what's needed.
Get a Decision
Your advisor packages your file and takes it to the lenders most likely to fit it, then walks you through the offers that come back. You will see the full terms (rate, monthly payment, and term length) before you commit to anything.
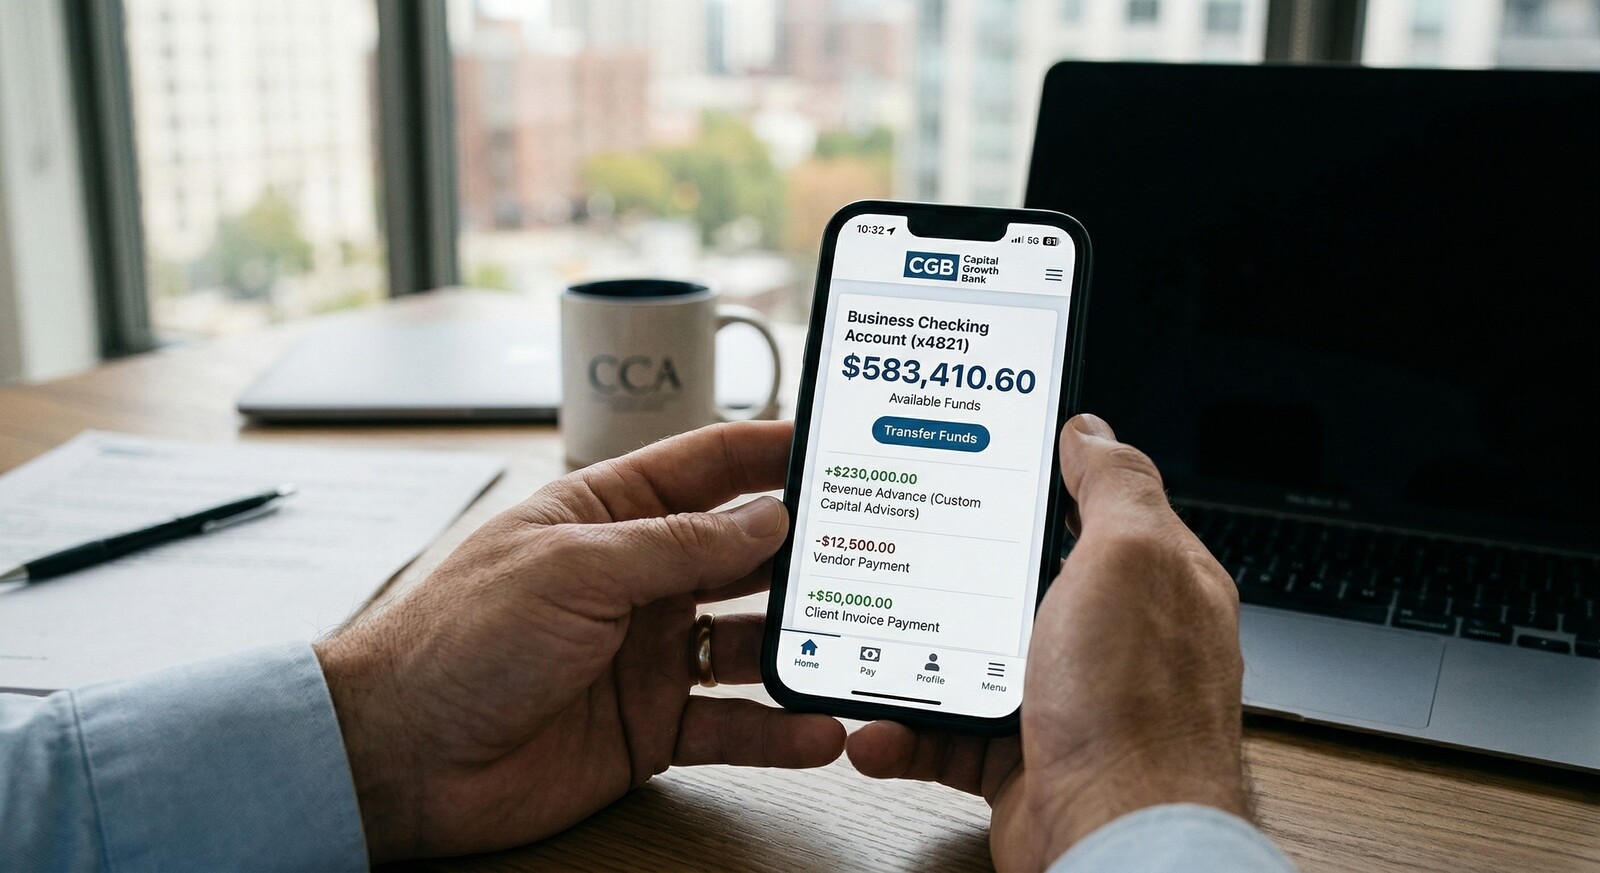
Receive Your Funds
Once you accept an offer, funds are typically deposited as a lump sum in as little as three business days. Use the capital for the investment you planned, on your timeline.
How long can a business term loan be?
Terms through our lender network run up to twelve years, with a minimum funding amount of $25,000 and amounts up to $500,000. Where a given file lands inside that range depends on the lender, the purpose of the funds, the age and revenue of the business, and whether anything is pledged as collateral. Longer horizons are typically reserved for larger, asset-backed, or clearly-documented uses.
We do not know your term before we have seen your documents, and we will not pretend otherwise. What we can tell you early is which lenders in our network write the horizon you are asking for, so you are not spending two weeks in an application that was never going to reach twelve years.
How fast can a long-term business loan be approved and funded?
Term loans are the slower end of business financing, and that is a fair trade for the longer horizon and the lower payment. In a typical file, an advisor reviews your documents and comes back with structured options in as little as one business day, and funds land as fast as three business days after you accept. Files that need collateral valuation, a landlord waiver, or additional tax documentation take longer.
If you need capital faster than a term loan can move, say so at the start. A line of credit or a revenue advance can often fund in a fraction of the time, and it is a better conversation to have on day one than on day ten. For a product-by-product breakdown, see how fast a business can get funded.
Speed depends on the lender, the completeness of your file, and your business profile. Nothing here is a commitment to a timeline or an approval.
What can you use a business term loan for?
Term loans are best suited for significant, planned investments with a clear long-term return across the industries we finance.
Fund Expansion Projects
Open new locations, renovate existing facilities, or scale operations with the substantial capital a term loan provides, without depleting your working capital reserves.

Stabilize Cash Flow
Smooth out seasonal dips and slow periods by securing a term loan that covers payroll, overhead, and operating costs while you focus on long-term growth.

Acquire Inventory in Bulk
Purchase inventory at volume to lower per-unit costs, meet peak demand, and ensure reliable supply, financed over a term that aligns with your revenue cycle.
How does a long-term loan compare to an SBA loan or a bank loan?
Three sources of long-horizon capital, three different trades.
A conventional term loan through a non-bank lender is the fastest of the three and the most flexible on credit profile and time in business. Terms typically top out lower than an SBA loan, and the cost of capital is usually higher than a bank would charge a borrower it wants.
An SBA loan offers the longest terms and generally the lowest cost of the three, backed by a partial government guaranty. It also asks for the most documentation and the most patience. The SBA 7(a) program caps at $5 million. If your timeline allows for it and your file is clean, it is often the best economics available.
A conventional bank term loan sits in between on cost and speed, and is the hardest of the three to qualify for. Banks typically want multiple years of profitable operating history, strong personal credit, and often collateral.
The honest summary: if you have the time and the documentation, start with the SBA or bank path. If you need the capital inside a normal business quarter, a term loan through a broker network is usually the realistic answer. We will tell you which of those you are, and if a bridge is the right way to hold you over while an SBA file works its way through, we will say that too. See SBA loan vs conventional business loan and bridging while you wait for SBA approval.
How does a business term loan compare to other financing?
| Term Loan | Small Business Loan | Equipment Financing | Line of Credit | |
|---|---|---|---|---|
| Up To | $500k | $1.5M | $2M | $150k |
| Term | Up to 12 years | 4–24 months | 6–24 months | Revolving |
| Repayment | Fixed monthly | Daily or weekly | Fixed monthly | Draw & repay |
| Funding Speed | 3 business days | 24 hours | 24 hours | 24 hours |
| Time in Business | 2+ years | 6+ months | 6+ months | 6+ months |
| Best For | Long-term strategic investment | Working capital & growth | Equipment purchases | Ongoing cash flow needs |
Not sure which product fits? Talk to a Capital Advisor →
When is a term loan the wrong choice?
Four situations where we will tell you to do something else.
Your cash need is recurring, not one-time. A term loan gives you the money once. If the underlying problem is a gap that reopens every quarter, you will be back for a second loan within the year. A line of credit is built for that shape.
You are financing receivables that already exist. If the money is already owed to you, borrowing against it through invoice factoring is usually cheaper and faster than adding a twelve-year obligation.
You already carry several advances or short-term positions. We do not chase consolidation deals. Layering a large term loan on top of stacked short-term debt rarely fixes the underlying math, and a lender who tells you it will is selling, not advising. The honest first step is a hard look at what you are already paying and to whom.
The purchase has a short useful life. Do not finance twelve months of consumables over twelve years.
Common Questions
Big Plans Deserve
Long-Term Capital.
Apply today. A Capital Advisor will review your business and structure an offer built around your growth plan, not a generic template.