
Inventory Loans,
Financing
& Funding
Last updated: July 2026
Stock the products your customers need, before the revenue arrives to fund it. Inventory financing lets you order ahead, expand product lines, and prepare for peak seasons without draining working capital. For materials consumed on a specific job, see financing to buy materials.
Financing at a Glance
When do you need inventory financing?
Inventory purchases are often your biggest lump-sum expense. We give you the capital to buy what you need, before revenue arrives, so you are never caught understocked during your highest-demand periods.

Buy Before You Sell
Most inventory-based businesses must purchase stock weeks or months before it converts to revenue. Inventory financing bridges that gap, letting you order ahead from suppliers without waiting for existing sales to fund the next purchase cycle.
Don't Miss Peak Seasons
Seasonal demand windows are time-sensitive. Whether you're stocking for the holiday rush, summer season, or any other peak period, financing lets you acquire inventory ahead of the curve, not scrambling to restock after demand has already arrived.
Protect Your Operating Capital
Large inventory buys shouldn't come at the cost of payroll, rent, or other operating needs. Inventory financing keeps those costs separate, so your cash reserves stay available for running the business while the loan repays as stock moves.
Fast Enough for Supplier Windows
Bulk purchase discounts, limited-time supplier pricing, and warehouse availability don't wait. We deliver decisions often within hours and fund within 24 hours, so you can act on inventory opportunities before they close.
How does inventory financing work?
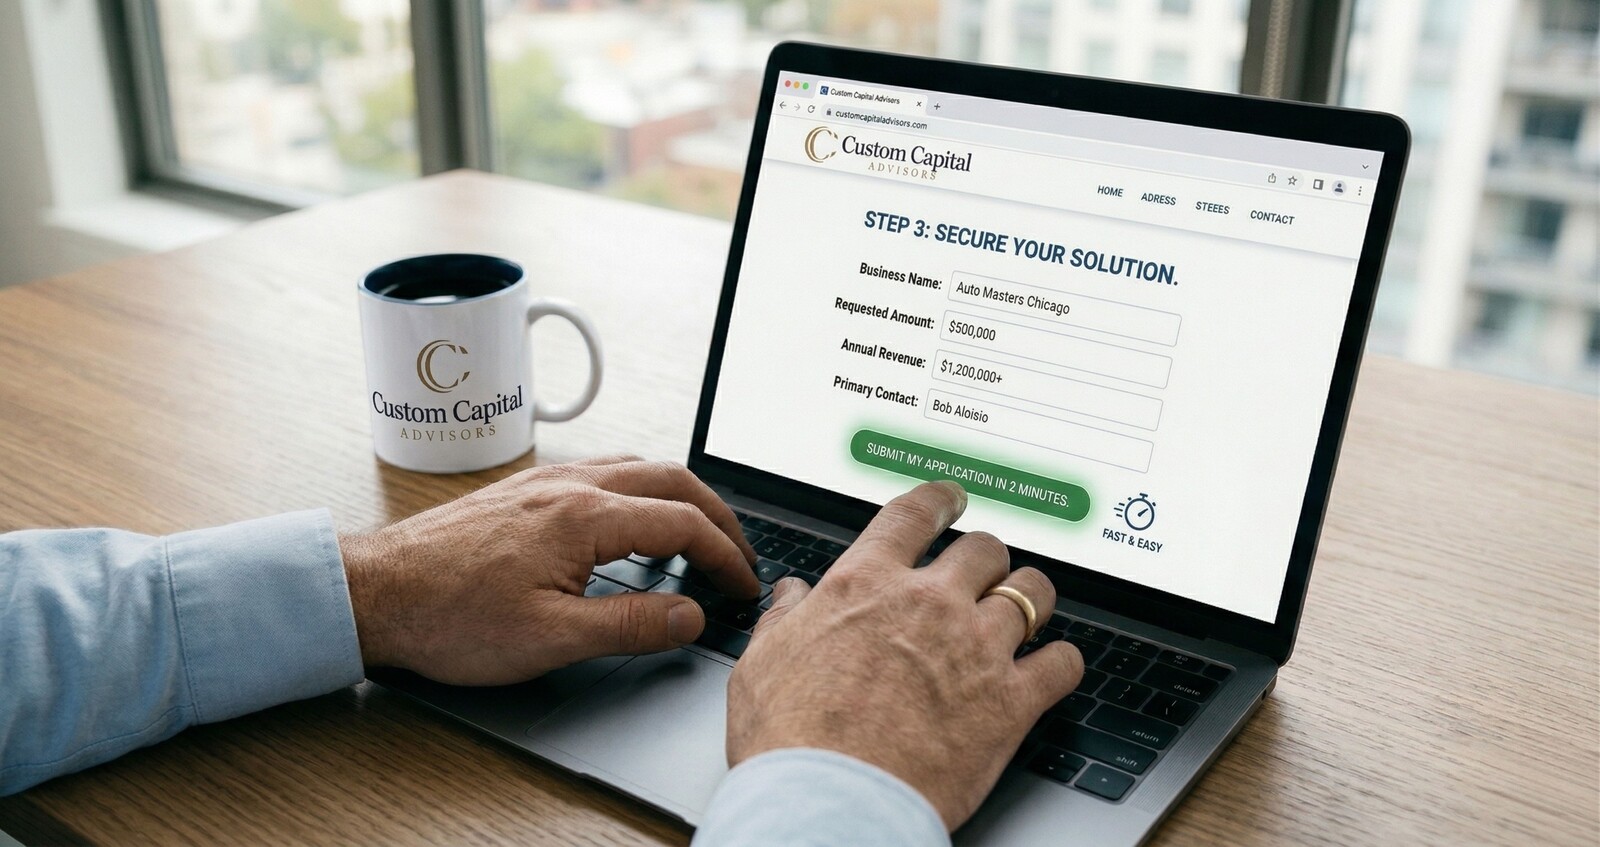
Apply Online in Minutes
Submit a brief application and connect with a dedicated Capital Advisor. Explain your inventory situation (upcoming seasonal buy, supplier opportunity, or product line expansion) and they'll guide you to the right structure.
Get a Decision
Your advisor reviews your revenue profile and presents a clear funding offer with transparent terms. Often the same day, giving you time to act on pricing windows, supplier availability, or seasonal deadlines.
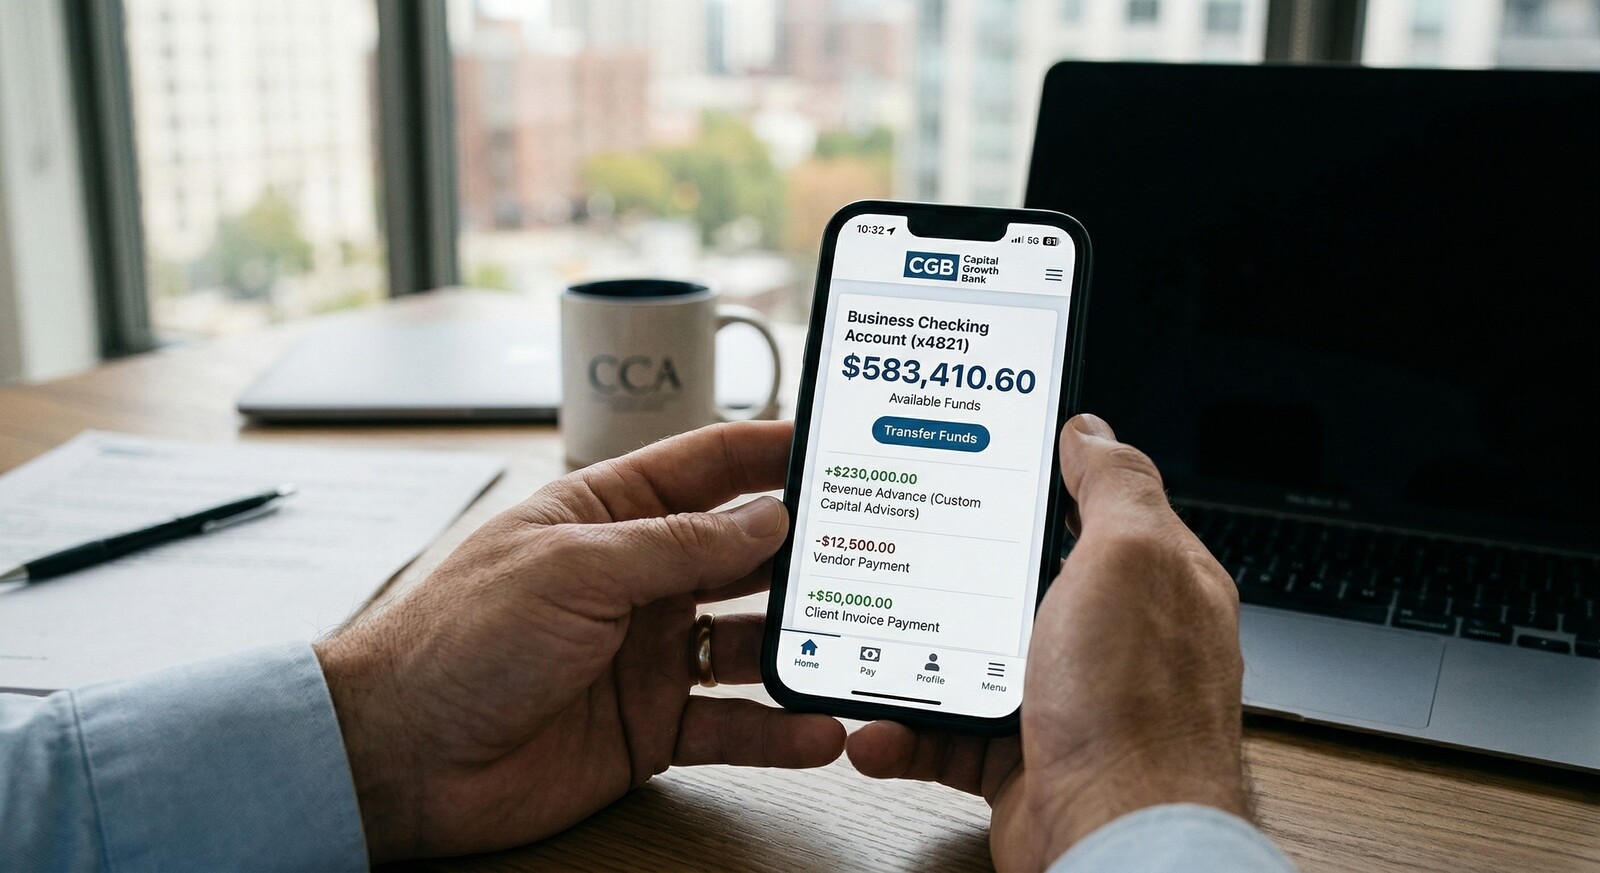
Stock Your Inventory
Receive your funds as fast as 24 hours after acceptance. Place your orders, stock your shelves or warehouse, and repay naturally as inventory converts to revenue.
What can you use inventory financing for?
Businesses rely on inventory financing to order products before they sell them, giving them the stock on hand to meet customer demand without waiting on revenue to fund the purchase.
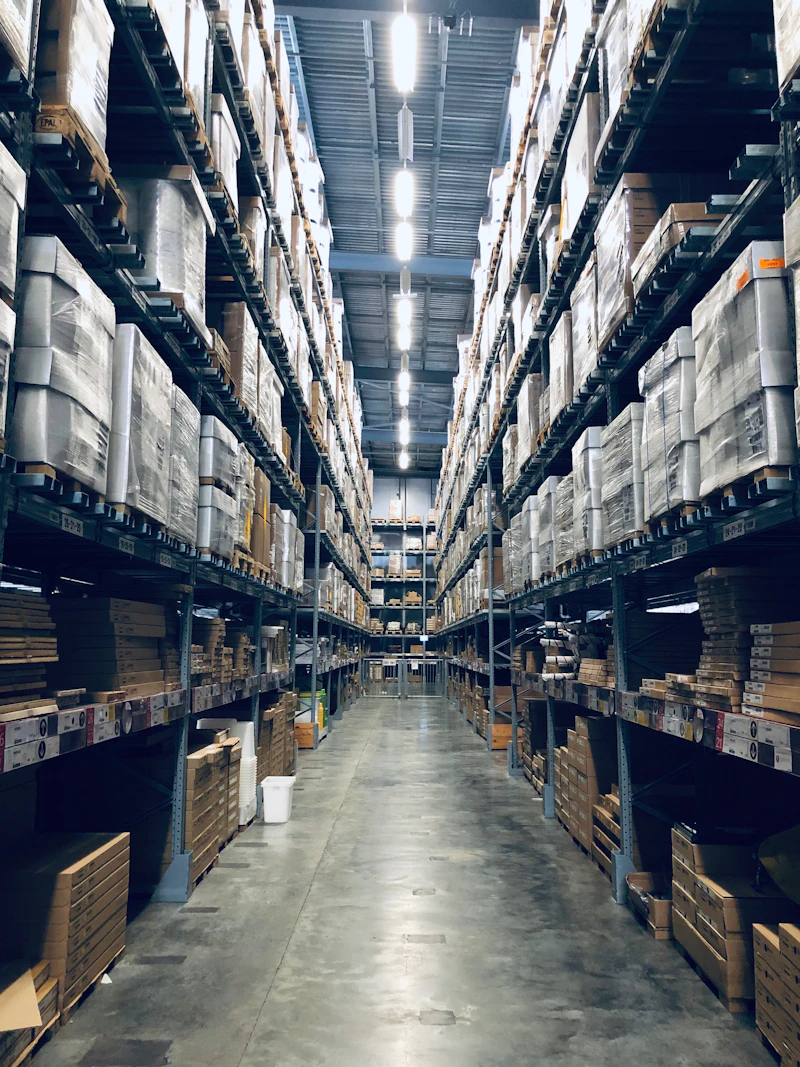
Expand Product Lines
Add new SKUs, test new categories, or extend into adjacent product lines, with capital to make the inventory investment before those items generate revenue.
Meet Seasonal Demands
Stock shelves and warehouses ahead of peak seasons, before the revenue arrives to fund it. Prepare for holiday rushes, seasonal peaks, and high-demand windows without draining cash reserves.
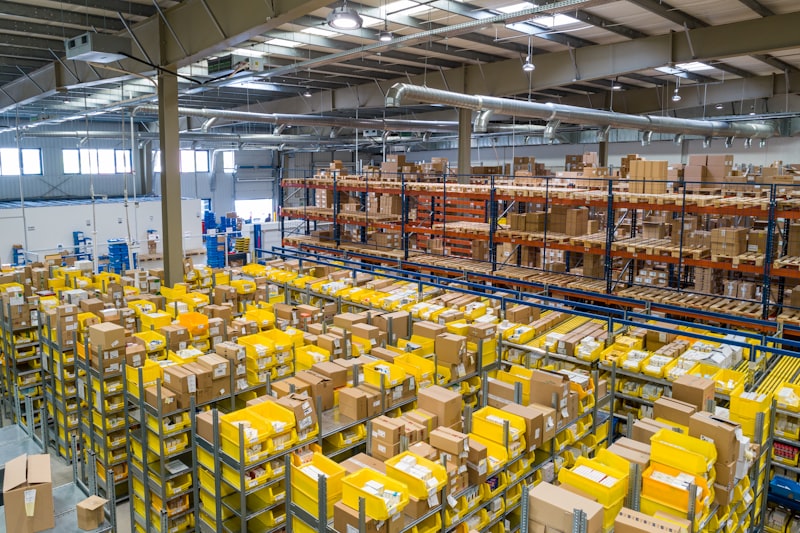
Protect Operating Capital
Keep payroll, rent, and operations running while funding large inventory purchases separately, so one big buy doesn't disrupt every other part of the business.
What are the best financing options for buying inventory?
Not every inventory situation calls for the same structure. Explore our products to find the right fit for your purchasing cycle, volume, and repayment preferences.
Small Business Loan
Lump-sum capital with no use restrictions: the most direct option for funding a large one-time inventory purchase or seasonal restocking buy.
Learn MoreRevenue Advance
Upfront capital repaid as a percentage of your daily revenue, automatically adjusting on slower days as inventory moves and sales vary.
Learn MoreLine of Credit
Revolving access to capital: draw for inventory purchases as needed, repay as stock converts to sales, and draw again for the next cycle.
Learn MoreEquipment Financing
When inventory operations require storage upgrades, warehouse equipment, forklifts, or refrigeration. Finance the asset separately from the inventory itself.
Learn MoreTerm Loan
Structured repayment for larger, recurring inventory investments, with fixed payments and defined terms that make budgeting predictable.
Learn MoreNot Sure Which Fits?
Your Capital Advisor will review your inventory purchase cycle and revenue profile, then recommend the financing structure that best fits your business.
Let's TalkHow do you qualify for inventory financing?
Qualifying for inventory financing turns on a narrower set of facts than most business borrowing, because the inventory itself carries part of the risk. Lenders want to see that the goods are sellable, that they move, and that the business has a record of turning stock into revenue.
In practice a lender reviewing an inventory request looks at four things.
Sales history on the inventory being financed. A lender is underwriting the sell-through, not the purchase. Twelve months of revenue showing that comparable stock moved at a predictable rate is worth more than a large balance sheet with no movement behind it.
Inventory turnover. How many times a year the business cycles its stock tells a lender how quickly the financing repays itself. Faster turnover generally supports better terms because the repayment source is closer in time.
Time in business and bank activity. Most inventory financing sits behind a minimum operating history, commonly six months to two years depending on the structure, along with business bank statements that show consistent deposits.
What the inventory is. Goods with a broad resale market, a stable price and a long shelf life are easier to finance than perishable, seasonal-only or highly specialised stock. This is where two businesses with identical financials get different answers.
Credit matters, and it matters less here than it does on unsecured borrowing, because the stock and the sales behind it carry weight of their own. CCA is a brokerage rather than a direct lender, so a file that does not fit one lender's inventory criteria is often placed with another whose criteria are built differently. Meeting these does not guarantee approval, and nothing about terms is fixed before documents are reviewed.
How much inventory financing can a business get?
The amount available is usually tied to the inventory rather than to a flat number, which is why two businesses with the same revenue can be offered very different limits.
Most structures size the facility against either the value of the stock being purchased or the value of the inventory already on hand. Advance rates against existing inventory are typically well below the retail value of the goods, because a lender is pricing what the stock would realise in a forced sale rather than what it would earn over a normal season. Financing a specific purchase order or supplier invoice can support a higher proportion, because the goods are identified, priced and often pre-sold.
Three things move the number more than anything else:
- Turnover rate. Stock that cycles several times a year supports a larger facility than the same dollar value sitting still.
- Concentration. A business whose inventory is spread across many products and many customers is generally sized more generously than one whose stock and sales sit with a single line or a single buyer.
- Whether the goods are already committed. A confirmed order behind the stock changes the risk picture substantially.
A business that needs more than its inventory alone supports is often better served by combining structures, for example a revenue advance or a line of credit alongside the inventory facility, so the stock is not asked to carry the whole request. That combination is the part most owners do not know is available, and it is the part a brokerage is useful for.
How fast can a business get inventory financing?
Speed is usually the reason inventory financing is being considered at all. A supplier window, a seasonal buy or a container already in transit does not wait for a sixty-day underwrite.
Timelines depend on structure. A revenue advance or a working-capital facility used to buy stock can move in as little as 24 hours once a complete file is in, because the underwriting leans on bank activity that is already documented. An inventory-secured facility or an asset-based line takes longer, commonly one to three weeks, because the stock has to be valued and in some cases inspected. A term loan sits between the two.
What actually determines the timeline, more often than the product, is document readiness. Files that move fastest arrive with recent business bank statements, a current inventory list with costs and quantities, the supplier invoice or purchase order being financed, and last year's business tax return already assembled. Files that stall are usually waiting on one missing document rather than on a lender decision.
Because CCA places files with multiple funding sources rather than lending directly, a request that is time-critical can be routed toward the structures that underwrite fastest, with the slower and often cheaper options presented alongside so the trade is visible rather than assumed.
Common Questions
Stock What You Need.
Sell Without Limits.
Apply today and get a decision often within hours. Capital in hand within 24 hours of acceptance, so your shelves stay full when demand peaks.