
Service Business
Loans &
Financing
Last updated: July 2026
From salons to hotels to marketing agencies, we provide all types of service-based businesses with fast, flexible financing built around how service companies operate.
Financing at a Glance
What makes service business financing different?
Service businesses often lack the hard assets that traditional lenders require as collateral. We evaluate financing based on revenue performance, not what you can pledge.
Revenue-Based Approval, Not Asset-Based
Service businesses often don't hold significant physical collateral. We evaluate your business based on revenue performance, making financing accessible even without equipment, real estate, or hard assets to pledge.
Financing That Covers What You Actually Need
Whether it's new hires, equipment, a renovated studio, or working capital to bridge a slow period. Our products are flexible enough to cover the specific needs of service-based operations without use restrictions.
Fast Enough for Real-World Business Decisions
Service businesses move quickly, new client contracts, expansion opportunities, and equipment needs don't wait. We deliver decisions often same day so you can act on opportunities in real time.
Works for a Wide Range of Service Industries
From solo practitioners to multi-location service operations, we've worked with salons, agencies, cleaning companies, consultants, event businesses, hotels, and dozens of other service verticals.
How does a service business loan work?
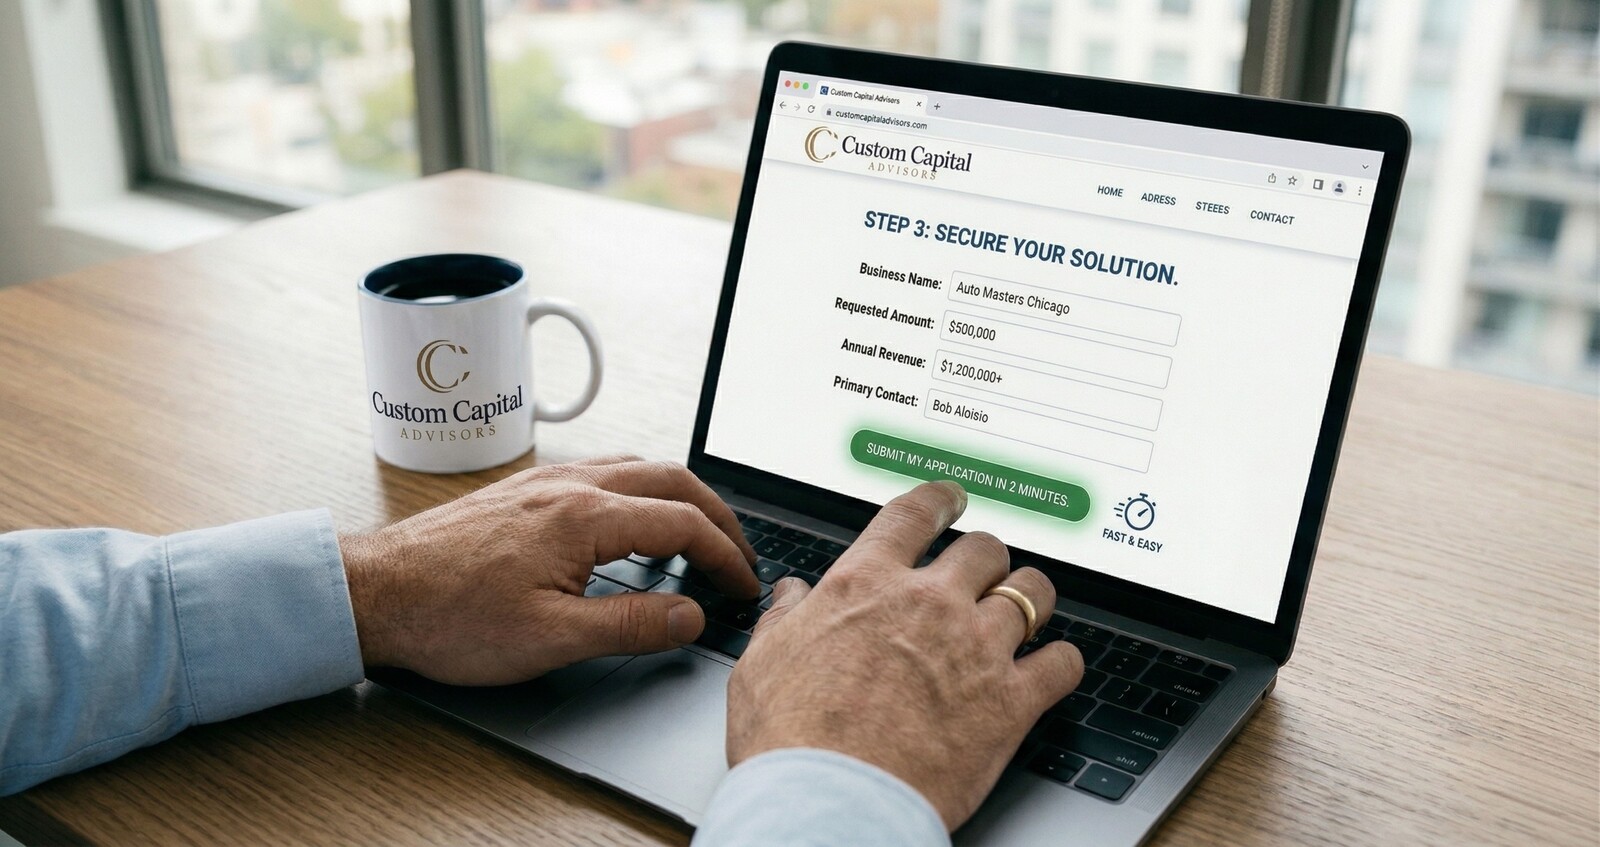
Apply Online in Minutes
Submit a brief application and connect with a dedicated Capital Advisor. Describe what your service business needs, equipment, staffing, a renovation, or working capital, and they'll guide you from there.
Get a Decision
Your advisor reviews your business's revenue profile and presents a clear funding offer with transparent terms. Often a same-day decision, with no excessive paperwork, no unnecessary delays.
Access Your Funds
Receive a lump-sum deposit as fast as 24 hours after accepting your offer. Hire staff, buy equipment, renovate your space, or handle any other business priority, immediately.
What can you use a service business loan for?
Service businesses use financing to buy equipment, expand their team, renovate their space, and bridge cash flow gaps, all without pledging hard assets as collateral.
Equipment Purchases
Buy computers, salon chairs, service vehicles, commercial equipment, or any tools your business relies on, without tapping into working capital.
Growth & Expansion
Add new hires, lease additional space, open a second location, or invest in marketing to grow your client base and service capacity.
Renovations & Build-Outs
Customize your space to reflect your brand, improve the client experience, and create an environment that supports long-term growth.
What are the best financing options for service businesses?
Not every financing structure fits every service business. Explore our products to find the right fit for your operation.
Small Business Loan
Lump-sum working capital with no use restrictions. Cover payroll, buy equipment, fund a renovation, or address any other service business need.
Learn MoreRevenue Advance
Upfront capital repaid as a percentage of your daily revenue, ideal for service businesses with variable monthly billing and seasonal swings.
Learn MoreEquipment Financing
Purpose-built for service equipment, from salon chairs and commercial tools to computers and service vehicles. Own it outright at the end.
Learn MoreLine of Credit
Revolving access to capital, draw what you need, repay, and draw again. Great for managing ongoing operational expenses and cash flow gaps.
Learn MoreTerm Loan
Long-term structured repayment for major planned investments, opening a new location, large renovations, or significant equipment overhauls.
Learn MoreNot Sure? Ask Us.
Your Capital Advisor will review your service business's revenue profile and recommend the financing structure that fits your specific situation.
Let's TalkHow do you qualify for a service business loan?
Qualification comes down to four inputs: operating history, monthly deposits, the owner credit profile, and what the last few months of business bank statements show. Service firms are often stronger on deposits than owners expect, because retainers, recurring contracts, and repeat clients produce steadier deposits than one-off project work.
Start with three to six months of business bank statements, a completed application, and a plain description of what the money is for. Custom Capital Advisors is a brokerage, not a direct lender. We do not set terms and cannot promise an approval or a rate before a lender has reviewed the file. What we can do is say honestly whether the file is likely to clear, and say so early if it is not.
What do lenders look for in a service business?
A service business has very little a lender can repossess, so underwriting leans on things that do not sit on a balance sheet.
- Deposit consistency rather than deposit size. Twelve steady months read better than one exceptional month followed by a thin one.
- Client concentration. One client as most of revenue is underwritten differently from forty similar clients at identical revenue.
- Contract and retainer structure. Recurring revenue is treated as more predictable than project revenue billed job by job.
- The gap between invoicing and payment. Lenders look at how long receivables actually take to clear, not what the terms say.
- Owner credit weighed against revenue rather than in isolation. Credit shapes pricing more often than it decides the answer.
None is pass or fail alone. Together, they decide which funding partner sees the file first.
How much can a service business borrow?
It depends on the structure, and the structures differ by an order of magnitude. A revenue advance sized against monthly deposits sits in a different range than a line of credit against receivables, which differs again from a term loan supported by several years of returns. Rather than quote a number we cannot stand behind, we will say which structures the business can realistically reach and roughly what each would cost, before applying anywhere. The conversation takes one call and does not affect credit.
What documents do you need to apply for service business financing?
The starting package for most working capital structures is three to six months of business bank statements, a completed application, and a photo ID. That is usually enough for a first read on which lenders are worth approaching. Larger or longer-term structures ask for more: business tax returns, a profit and loss statement, an accounts receivable ageing report where receivables are part of the story, and a considerably longer list for SBA-backed requests. Full packages sent on the first request are reviewed faster, and decisions on the fastest structures can come in as little as a few hours once statements are in hand.
Common Questions
Your Service Business
Deserves Better Capital.
Apply today and get a decision often within hours. Capital in hand within 24 hours of acceptance, so you can focus on serving your clients.